Why Maxforce
Motorized Hurricane Screen

MAXFORCE PROVEN PROTECT
Engineered For Excellence
For nearly two decades, MaxForce has manufactured hurricane screens to meet the most demanding building code, the High Velocity Hurricane Zone of Miami-Dade. The MaxForce track is our newest version of the fixed track we have used with great success for high wind applications all over the globe.
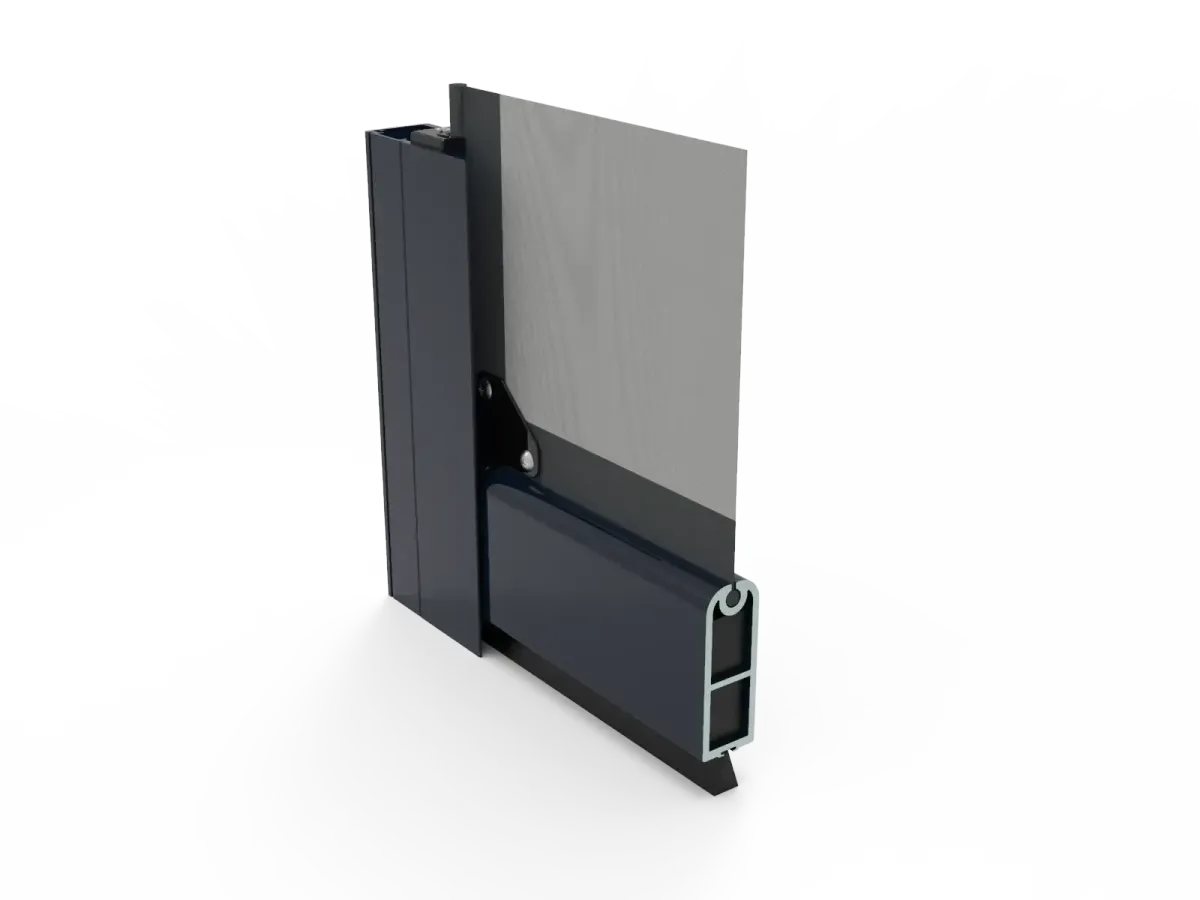
The benefits of a fixed track are unmatched strength - this is important when designing a screen system for hurricanes. When you want the strongest system available, and a proven veteran of many hurricanes, the MaxForce Hurricane Track is your best choice.
MAXFORCE THE #1 MOTORIZED HURRICANE SCREEN
Contact A+ Certified MaxForce Screen Dealer Today...
HEADACHE-FREE
Exclusive self-tensioning system eliminates 99.9% of screen issues. No track adjustments, broken zippers, or dislodged screens.
LIFETIME WARRANTY
Exterior shade screens reduce cooling bills and MaxForce hurricane screens reduce insurance premiums in hurricane zones.
HURRICANE STRONG
Our MaxForce tracks and advanced hybrid ballistic fabrics withstand 150+ mph winds. Approved by Florida Building Commission for hurricane zones. Lab and real-world tested.
BUILT TO LAST
We use marine-grade materials such as powder-coated aluminum, UV-protected nylons, stainless steel fasteners, and premium fabrics. Resists corrosion, rust, and screen failure.
COST-SAVING
Exterior shade screens reduce cooling bills and MaxForce hurricane screens reduce insurance premiums in hurricane zones.
SMART CONTROLS
Control MaxForce screens via remote and
phone or integrate with popular home automation systems for advanced
capabilities.
SECURE TRACK
MaxForce Fix Hurricane Track holds firm under extreme loads
MAX CORROSION PROTECTION
Powder Coated Aluminum Protects your investment from exposer and corrosion.
HEAVY-DUTY DESIGN
Our screens are designed to withstand the extreme. High wind, Rain, or Shine, Dust Dirt, Dander, it doesn't matter. MaxForce Cover it all.
CUSTOM-MADE SCREENS
Tailor-made screens with vast color, fabric, and system options. Custom paint color and fabric matching are available.
MAXFORCE THE #1 MOTORIZED HURRICANE SCREEN
Contact A+ Certified MaxForce Screen Dealer Today...
MAXFORCE
Ready For Life's Storms
MAXFORCE HURRICANE SCREEN SYSTEM
A Certified, Tested System...
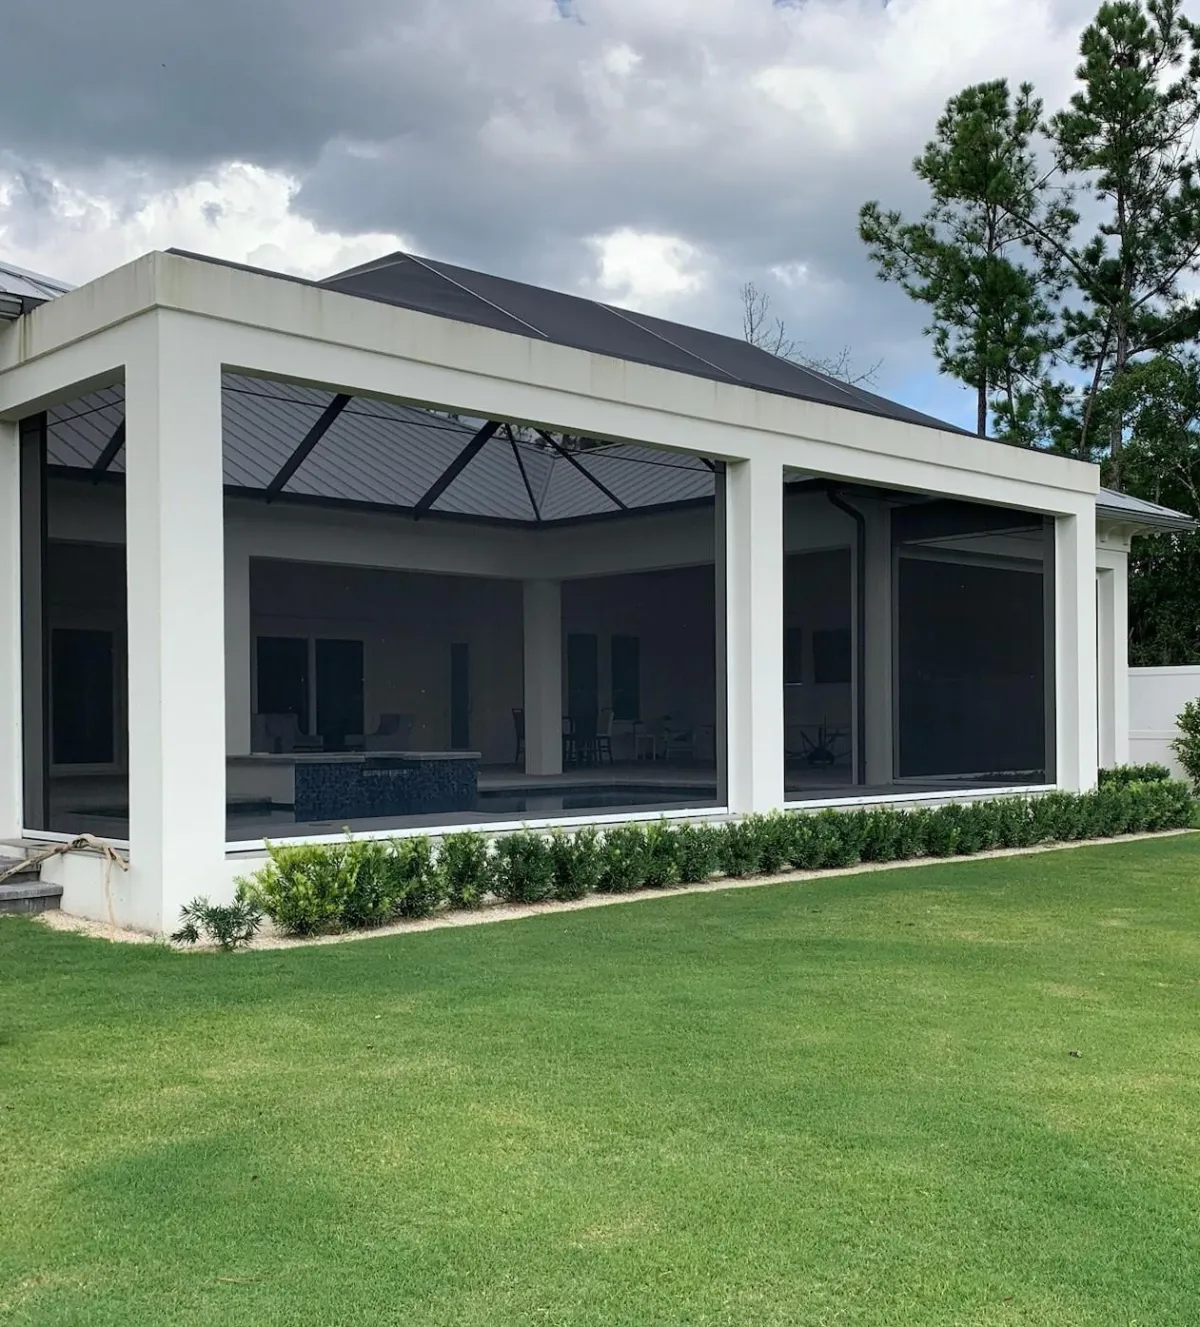
The MaxForce Hurricane Screen System meets or exceeds Miami-Dade and Florida Building Code requirements—the toughest hurricane codes on earth—for roll-down hurricane screens. Rated for the 185 MPH wind zone, and with real-world and certified testing. With spans of up to 25 feet, they exceed performance criteria for all local and International Building Codes.
MAXFORCE THE #1 MOTORIZED HURRICANE SCREEN
Contact A+ Certified MaxForce Screen Dealer Today...
THE MAXFORCE DIFFERENCE
Maxforce Hurricane Screen
MaxForce Hurricane Screens, powered by our MaxForce system, meet the toughest standards—including HVHZ certification in Miami-Dade and Broward. They last longer, resist more, and do more than any screen on the market—proven protection without compromise.
MaxForce Hurricane Screens —Delivers 365 days of perfect protection, rain or shine, on your patio and lanai. With the push of a button or a tap on the mobile app, your patio is storm-ready— furniture and openings fully protected in seconds.
MaxForce Hurricane Screens fabric blocks up to 95% of the sun’s damaging UV-rays while shielding against wind, rain, insects, dust, and debris. It also helps reduce heat and lower energy costs by limiting solar exposure—comfort and protection in one smart solution.
Like all Maxforce products, our MaxForce Hurricane Screens are highly customizable and built to order—made to fit your exact openings. No guesswork, no compromises—just precision-fit protection tailored to your space.
Pair our retractable MaxForce Hurricane Screens with other Maxforce screens for customized and independent solutions. Each screen operates independently, giving you the protection you want when you need it.
MaxForce Hurricane Screens offer built-in privacy without blocking your view. Like a two-way mirror, you can see out—but neighbors and passersby can not see in. It provides the perfect blend of openness and seclusion, day or night.
MAXFORCE THE #1 MOTORIZED HURRICANE SCREEN
Contact A+ Certified MaxForce Screen Dealer Today...
INTEGRITY MATTERS
How MaxForce Is Made Matters
AMERICAN INGENUITY
Made in the USA
Proudly Made in the USA—every MaxForce screen is built with American strength, precision, and pride. From the smallest components to the final assembly, our materials are sourced and manufactured right here in the United States. No outsourcing. No compromises. Just hardworking Americans protecting American homes with the toughest screen system on the market.
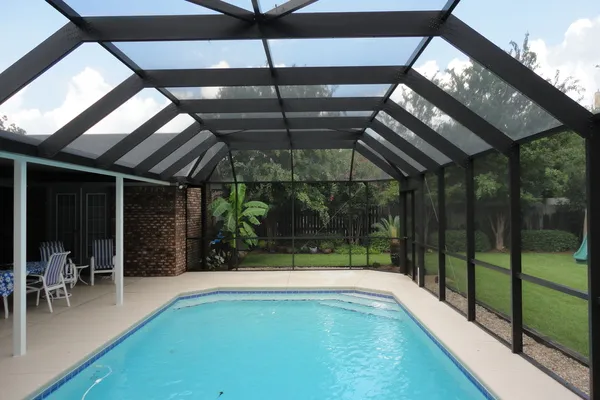
After Isaias: Walk Away From a Contractor Who Wants to Handle Your Insurance Claim
Part of our series on the 10 most common mistakes homeowners make after a hurricane damages their screen enclosure, pool cage, screen room, or patio cover.
It usually sounds helpful. "Don't worry about the insurance company, we'll handle all that." "Just sign here so we can talk to your adjuster." "We'll make sure insurance pays for a whole new cage." After a storm, with a hundred things on your plate, letting someone else deal with the claim can sound like a relief.
It's one of the clearest red flags you'll hear from a contractor.
Why it's a red flag
In Florida, contractors can't interpret your insurance policy, advise you about your coverage, or adjust your claim on your behalf unless they also hold a public adjuster license. A contractor offering to "handle" your claim is offering something they generally aren't allowed to do.
And they can't take over your benefits either. For property policies issued or renewed on or after January 1, 2023, Florida law voids any agreement that signs your post-loss insurance benefits over to someone else. If a contractor hands you paperwork that sounds like it gives them rights to your claim or your insurance check, stop and don't sign.
Phrases to listen for
"We'll handle your insurance company for you."
"Sign this so we can deal with your adjuster."
"We'll get insurance to pay for everything."
"We'll take care of your deductible," or "You won't pay a deductible."
"Just sign over the check and we'll take it from there."
That deductible offer deserves its own warning. You're responsible for your deductible. A contractor who offers to cover or waive it usually has to make up the difference by inflating the claim somewhere else, and that's insurance fraud. Florida insurers warn that both the contractor and the homeowner who goes along with it can face felony charges.
"If somebody offers to cover your deductible, they're not doing you a favor. They're asking you to put your name on something you don't want your name on." — Eric Vanheteren, Aluminum Building Systems
What a good contractor actually does
A reputable contractor's role is simple: assess the damage, give you a detailed written estimate, and do the work. If your adjuster calls or meets the contractor on site, the contractor can explain their own estimate: what's damaged, what the repair involves, and what it costs. That's where it stops. You own your claim. You decide what to submit and how to deal with your insurance company.
If you want professional help with the claim itself, the legal options are a licensed public adjuster or an attorney. You can verify a public adjuster's license through the Florida Department of Financial Services.
"We'll give you a detailed written estimate to send your insurance company. The claim itself is yours. Anybody who tells you otherwise is selling you something." — Eric Vanheteren, Aluminum Building Systems
If something feels wrong
If a contractor pressures you to sign over your claim, offers to cover your deductible, or suggests anything that sounds like padding the claim, walk away. You can report suspected insurance fraud to the state's Fraud Free Florida hotline at (800) 378-0445.
When you're ready
Next in this series: After Isaias: Don’t Rescreen Until Someone Checks the Frame
After Isaias: Walk Away From a Contractor Who Wants to Handle Your Insurance Claim
Part of our series on the 10 most common mistakes homeowners make after a hurricane damages their screen enclosure, pool cage, screen room, or patio cover.
It usually sounds helpful. "Don't worry about the insurance company, we'll handle all that." "Just sign here so we can talk to your adjuster." "We'll make sure insurance pays for a whole new cage." After a storm, with a hundred things on your plate, letting someone else deal with the claim can sound like a relief.
It's one of the clearest red flags you'll hear from a contractor.
Why it's a red flag
In Florida, contractors can't interpret your insurance policy, advise you about your coverage, or adjust your claim on your behalf unless they also hold a public adjuster license. A contractor offering to "handle" your claim is offering something they generally aren't allowed to do.
And they can't take over your benefits either. For property policies issued or renewed on or after January 1, 2023, Florida law voids any agreement that signs your post-loss insurance benefits over to someone else. If a contractor hands you paperwork that sounds like it gives them rights to your claim or your insurance check, stop and don't sign.
Phrases to listen for
"We'll handle your insurance company for you."
"Sign this so we can deal with your adjuster."
"We'll get insurance to pay for everything."
"We'll take care of your deductible," or "You won't pay a deductible."
"Just sign over the check and we'll take it from there."
That deductible offer deserves its own warning. You're responsible for your deductible. A contractor who offers to cover or waive it usually has to make up the difference by inflating the claim somewhere else, and that's insurance fraud. Florida insurers warn that both the contractor and the homeowner who goes along with it can face felony charges.
"If somebody offers to cover your deductible, they're not doing you a favor. They're asking you to put your name on something you don't want your name on." — Eric Vanheteren, Aluminum Building Systems
What a good contractor actually does
A reputable contractor's role is simple: assess the damage, give you a detailed written estimate, and do the work. If your adjuster calls or meets the contractor on site, the contractor can explain their own estimate: what's damaged, what the repair involves, and what it costs. That's where it stops. You own your claim. You decide what to submit and how to deal with your insurance company.
If you want professional help with the claim itself, the legal options are a licensed public adjuster or an attorney. You can verify a public adjuster's license through the Florida Department of Financial Services.
"We'll give you a detailed written estimate to send your insurance company. The claim itself is yours. Anybody who tells you otherwise is selling you something." — Eric Vanheteren, Aluminum Building Systems
If something feels wrong
If a contractor pressures you to sign over your claim, offers to cover your deductible, or suggests anything that sounds like padding the claim, walk away. You can report suspected insurance fraud to the state's Fraud Free Florida hotline at (800) 378-0445.
When you're ready
Next in this series: After Isaias: Don’t Rescreen Until Someone Checks the Frame
COMPANY
QUICK LINKS
LEGAL
FOLLOW US


© 2026 Fenetex Lead Nexus | A Fenetex Corporation | All Rights Reserved